Currency overlap and portfolio accounting units
Do not infer diversification, joint loss or account equity from separately sized pair examples.
An instrument count does not describe a portfolio
Two pair labels can share a currency or funding source while having different base units, quote conventions and reporting amounts. A count of positions is not notional, account risk or an independence certificate. Preserve each actual product, quantity, direction, time, price basis and cash conversion before aggregating economics. The original USD sizing tool controls one entered planned scenario, not a joint tail loss. The new cash lens also handles one fixed-unit comparison only. The site observes no actual portfolio, correlation matrix or funded set of simultaneous trades.
An authored reporting example names the missing quantity path
Imagine two fictional records both displaying 10 USD price change, one from a USD quote and another from a JPY quote converted into USD. Equal reporting cash does not identify equal base quantity, exchange-rate exposure or independent event sensitivity. The learner needs each original amount and conversion direction before even the accounting can be reconstructed. No actual pair holdings or measured covariance is supplied. The completed finding is incomparable exposure information despite a shared displayed result. It is not a claim that either position is suitable, hedged or statistically diversified.
Simultaneous cash needs consistent inclusions
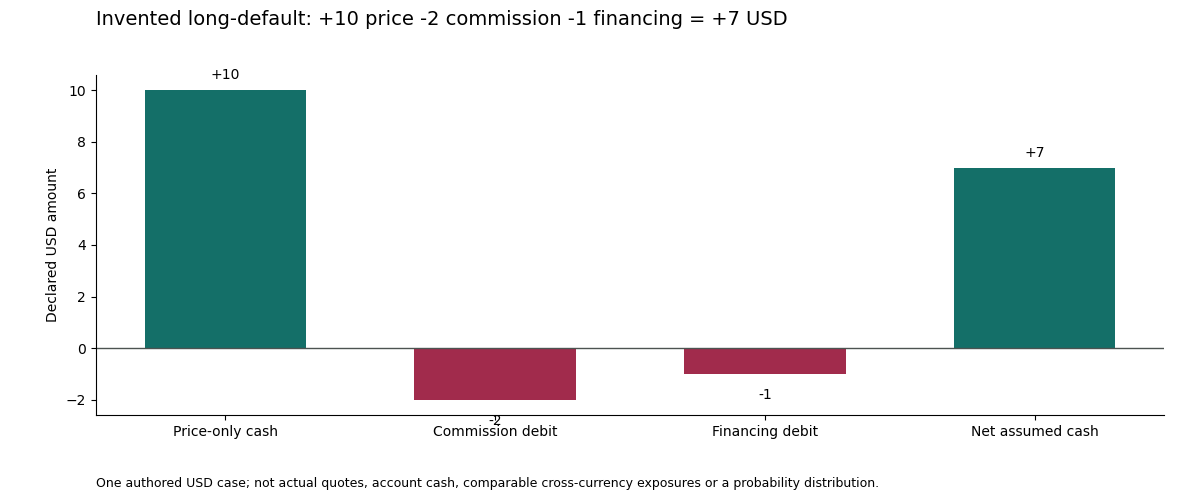
Actual account aggregation should preserve fees, signed financing, conversion events, open positions and capital flows under a fixed convention. A gross price percentage cannot be added to a cash amount or treated as compounded equity without defining weights and timing. The seven fictional cash cases are alternatives, not simultaneous portfolio holdings. The plot therefore shows authored branches rather than a diversified performance distribution. No actual mark, margin, liquidation, funding capacity or maximum loss is computed. A real statement and complete eligible period would be needed for stronger account-level claims.
Overlap can constrain implementation without ranking entries
Portfolio economics and overlap can evaluate, reject or size a frozen experiment, but cannot redefine the canonical causal entry ranking after seeing outcomes. Keep entry identity, selected native exit, full trial register and independent master unchanged. The website supplies no real instrument adapter, calibration or production allocation. Provider descriptions likewise do not establish current pair rights or receiver quantities. Their producing and receiving records remain distinct. Public mechanism references and independently checked equations support unit literacy, not independent financial observations or a personally appropriate portfolio recommendation.
Filled fictional forex case
Two fictional 10 USD displays still lack the original quote amounts, quantities and shared event sources needed to compare exposure. No joint loss, correlation or diversification is inferred. The complete teaching conclusion is an explicit missing portfolio contract; the seven cash branches cannot be assembled into a funded account history.
| Object | Record | Bounded finding |
|---|---|---|
| Reporting amount | 10 USD in two examples | Not equal exposure |
| Original units | Not joined | No portfolio inferred |
| Joint tail/correlation | Absent | Not estimated from fiction |
Primary references and scope
Source checks: 13-14 October 2026. Official mechanism descriptions are not this desk's paid-account test, independently captured fills or vendor-return audit.