Filled forex setup and cash workbook
Three comparable setup cards, nine conditional decisions and seven invented quote-to-account cash cases.
A complete condition is not a completed trade
The setup cards are authored exercises on fictional completed midpoint-style observations. Their prior levels and exact comparisons are declared before classification. Each keeps product/input basis, availability, reference, condition, invalidation, execution status and evaluation scope. Known session and event eligibility are required for teaching admission; absent context remains unresolved. A predicate failure is not an executed loss. The nine decisions are deliberately selected branches, not a sampled market population or independent research evidence. No win fraction, profitable rule, actual order or calibrated probability is computed from them.
The trend example requires two completed closes above a frozen level and a rising second close. Range requires a prior low below the lower band and a completed close strictly inside. Breakout requires a strict upper break within its declared chase limit. A favourable later chart cannot change an equality, failed return or missing context into the original admitted decision. The cards specify neither actual broker entries nor a financial exit experiment. Real research retains its canonical causal objective, frozen identity, one selected native exit and independently verified master.
Two closes over a prior reference
| Card field | Declared teaching contract |
|---|---|
| input_basis | Fictional completed midpoint-style observations; no actual product/feed |
| availability | Assumed complete before teaching classification; no real receiving trace |
| reference | Prior level 1.1000 |
| condition | Two completed closes both strictly above reference, second strictly above first |
| invalidation | A failed comparison or absent required session/event context does not admit the candidate |
| execution | Not evaluated; no broker order or hypothetical fill assigned |
| evaluation | No financial exit or independent master evaluated; real tasks retain canonical entry objective, frozen identity and one selected exit |
| Decision | Observation | Session | Event | State | Reason |
|---|---|---|---|---|---|
| trend-match | 1.1004 then 1.1007 | known eligible | known eligible | admitted | Both above 1.1000 and rising |
| trend-fail | 1.1004 then 1.0999 | known eligible | known eligible | failed | Second below reference and not rising |
| trend-context | 1.1004 then 1.1007 | not supplied | known eligible | unresolved | Required session state absent |
Boundary interaction and completed return inside
| Card field | Declared teaching contract |
|---|---|
| input_basis | Fictional completed midpoint-style observations; no actual product/feed |
| availability | Assumed complete before teaching classification; no real receiving trace |
| reference | Prior lower 1.0990 and upper 1.1010 |
| condition | Prior completed low below lower, current completed close strictly inside lower/upper |
| invalidation | No boundary interaction, close outside/on boundary, or missing required context |
| execution | Not evaluated; no broker order or hypothetical fill assigned |
| evaluation | No financial exit or independent master evaluated; real tasks retain canonical entry objective, frozen identity and one selected exit |
| Decision | Observation | Session | Event | State | Reason |
|---|---|---|---|---|---|
| range-match | Low 1.0988, close 1.0992 | known eligible | known eligible | admitted | Low below lower and close strictly inside |
| range-fail | Low 1.0988, close 1.0989 | known eligible | known eligible | failed | Close remains below lower |
| range-context | Low 1.0988, close 1.0992 | known eligible | not supplied | unresolved | Required event state absent |
Strict upper break within a chase cap
| Card field | Declared teaching contract |
|---|---|
| input_basis | Fictional completed midpoint-style observations; no actual product/feed |
| availability | Assumed complete before teaching classification; no real receiving trace |
| reference | Prior upper 1.1005; cap 0.0003 price units |
| condition | Completed close strictly above upper and distance no greater than cap |
| invalidation | Equal/below upper, excessive distance, or required context missing |
| execution | Not evaluated; no broker order or hypothetical fill assigned |
| evaluation | No financial exit or independent master evaluated; real tasks retain canonical entry objective, frozen identity and one selected exit |
| Decision | Observation | Session | Event | State | Reason |
|---|---|---|---|---|---|
| breakout-match | Close 1.1007 | known eligible | known eligible | admitted | 0.0002 break within cap |
| breakout-equal | Close 1.1005 | known eligible | known eligible | failed | Equality is not a strict break |
| breakout-chase | Close 1.1009 | known eligible | known eligible | failed | 0.0004 exceeds cap |
Keep the fixed cash object separate from the cards
The cash packet begins with fixed original whole base units and two manually entered bid/ask snapshots. Long assumes entry ask and exit bid; short assumes entry bid and exit ask. Price difference times units and direction produces quote cash. Subtract nonnegative whole-position quote commission and add signed quote financing, each converted at its declared account-per-quote rate. Spread gaps are displayed diagnostics, not an extra subtraction from side-based price change. No actual market feed, order sequence, availability, tax, margin or liquidation is supplied.
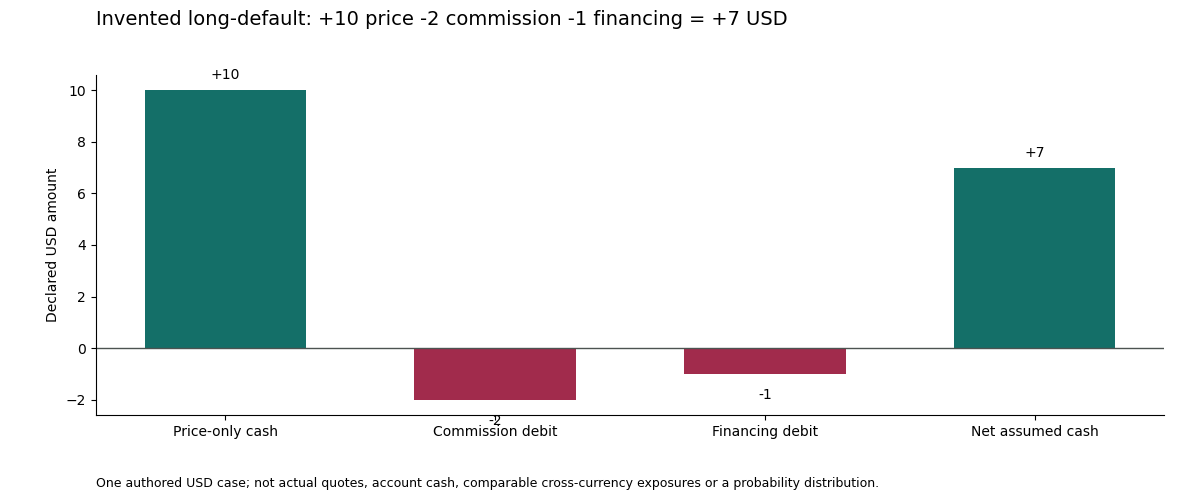
Default long inputs use 10,000 units, entry ask 1.1000 and exit bid 1.1010, with USD as quote and account. Gross price change is 10 USD, commission is 2 USD and financing is negative 1 USD, leaving 7 USD. The short alternative uses entry bid 1.0998 and exit ask 1.1012, producing negative 14 price change and negative 17 net after the same cash costs. The flat-midpoint case gives negative 5 net. These are alternative authored assumptions, not simultaneous positions, forecast returns or a statement that any actual broker filled the displayed prices.
Different conversions expose the reporting convention
The JPY example declares negative 1,200 price cash, 300 commission and negative 150 financing. Separate entered USD-per-JPY rates of 0.0065, 0.0064 and 0.0066 produce negative 10.71 USD net. Converting the combined negative 1,650 JPY at the one price rate would produce negative 10.725. Their 0.015 difference names an accounting assumption, not currency alpha or a correction to a real broker statement. The alternative reporting case uses declared CHF labels and amounts. No actual reference rate, currency identity or licensed market observation was authenticated.
The plot isolates the default USD reconciliation instead of placing different reporting currencies on one comparative scale. All seven cases remain downloadable with their exact labels, signs, rates and results, including neutral, adverse and positive branches. Python Decimal independently computes the reference packet while decimal.js performs the browser equations. Their agreement verifies software arithmetic only. Probabilities, actual fills and financial setup outcomes remain null; no genuine instrument adapter, calibrated model, subscriber route or independent economic master is produced by these teaching calculations.
Use the original budget tool for its own contract
The original worksheet still answers USD-account base-unit sizing under an entered planned budget, pip size, conversion, cost and increment. The new lens does not choose quantity or validate that budget. Its quote commission for the complete position is not the original form's USD commission per 100,000 units. Borrowing one quantity, another setup and a favourable cash path would invent a new study. The original ten-field rule workbench can retain those unresolved source requests without turning documented notes into an independent financial audit.
Downloads preserve the complete teaching object rather than an attractive winning subset. The card JSON names every predicate and execution limitation; its CSV contains all nine decisions. The cash CSV and JSON contain every input and expected amount. The public dependency licence applies to its own software, not third-party feeds or proprietary strategy history. The browser stores no draft, requests no account credentials and sends no assumptions to a broker. Cloud hosting owns publication continuity with personal computers off; temporary QA is not a production data source.
Complete invented cash references
| Case | Quote | Account | Price cash | Commission | Signed financing | Net cash |
|---|---|---|---|---|---|---|
| Long price gain, fee and financing debit | USD | USD | 10.0 | 2.0 | -1.0 | 7.0 |
| Short uses the opposite entered sides | USD | USD | -14.0 | 2.0 | -1.0 | -17.0 |
| Same midpoint, side-based friction | USD | USD | -2.0 | 2.0 | -1.0 | -5.0 |
| Declared financing credit | USD | USD | 10.0 | 2.0 | 3.0 | 11.0 |
| JPY quote, separate USD component conversions | JPY | USD | -7.8 | 1.92 | -0.99 | -10.71 |
| Zero side gap and zero additional cash | USD | USD | 10.0 | 0.0 | 0.0 | 10.0 |
| Declared alternative account conversions | USD | CHF | 8.0 | 1.62 | -0.79 | 5.59 |